1. Legal and Regulatory Risks of AI Payments
Under current law, AI cannot become a legal 'agent,' so all responsibility for damages from erroneous orders or malfunctions falls on the user. Additionally, directly providing credit card information to AI poses a high risk of violating terms and requires caution.
2. Security Challenges Posed by Autonomy
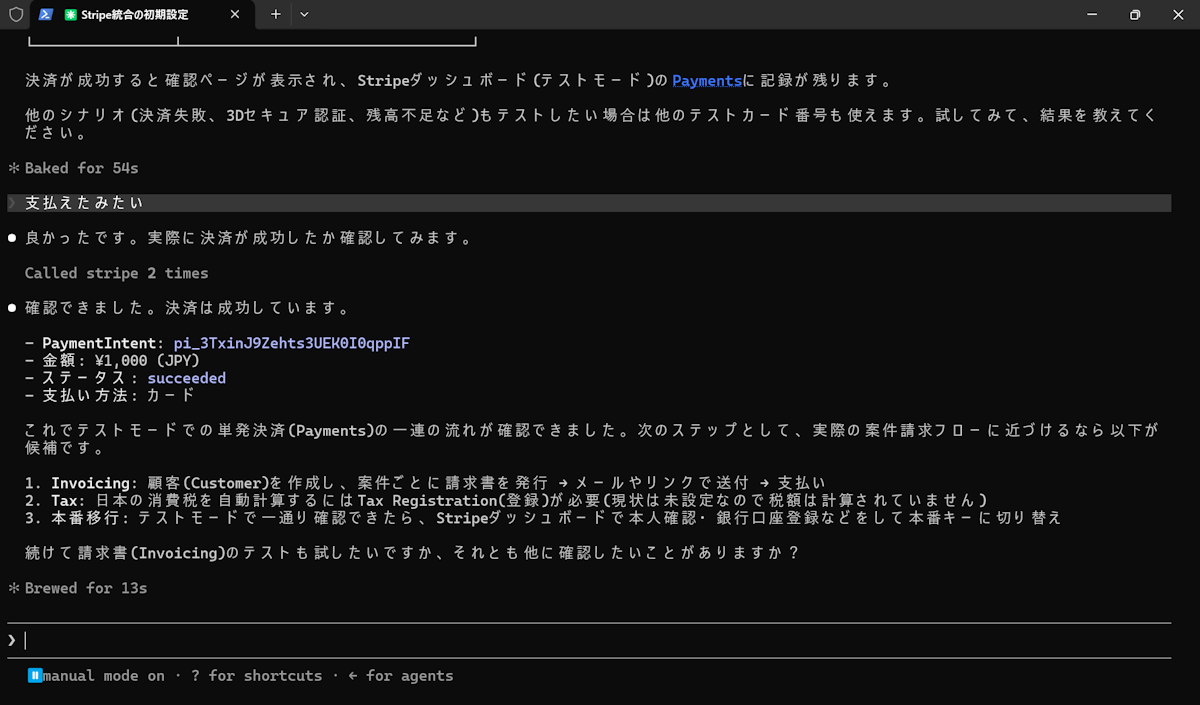
Demonstration tests using payment platforms have highlighted the risk of AI autonomously executing refund processes. Prioritizing convenience can easily breach the three-layer defense of authority and approval, making it essential to design systems that prevent critical operations.
3. Industry Measures for Secure Payments
In response to these challenges, international card brands are urgently developing technologies to ensure safety through dedicated tokens with limited use and transaction-specific intent verification. A fierce competition for dominance with condition-embedded stablecoins is expected to intensify.
An AI agent, acting on user instructions, autonomously makes decisions to execute purchases or transfers. In the U.S., companies like Visa and Mastercard have announced tokenized payment technologies specifically for agents, marking the beginning of a battle for international standardization.
Suddenly, are you using an AI agent? The definition of what constitutes an AI agent is still debated within the industry, but generally, it refers to an AI system that, when given a goal, autonomously makes decisions and actions to complete tasks.
There are three key points.
Recently, the technology to grant AI agents payment authority, enabling financial transactions at speeds unattainable by humans, has become a hot topic among financial professionals. It is said to be highly compatible with DeFi transactions, and individual users are reportedly increasing.
Let's first address the legal issues. To conduct regular commercial transactions online, credit card information registration is necessary.
Is it illegal under Japanese law to provide credit card information to an AI agent?
In conclusion, there is currently no law in Japan that deems it illegal to provide your own credit card information to an AI agent for payment. However, it is important to note that this is a legally complex area.
Fundamentally, AI agents cannot be legal 'agents' under civil law. Since agency actions under civil law assume a 'person,' the effects of orders and payments made by AI are attributed to the user.
Any damages from erroneous orders or illegal transactions that exceed the owner's intentions fall entirely on the AI agent user.
Furthermore, almost all card companies' membership agreements prohibit 'lending the card to third parties or disclosing the card number to third parties.'
No matter how well-trained your AI agent is, its actual entity resides on the AI vendor's server.
Actions that allow an AI on another's server to input and store card numbers may be interpreted as third-party disclosure, potentially excluding you from insurance coverage for misuse, or even resulting in card usage suspension or forced contract termination due to contract violations.
To avoid such issues, Visa and American Express's payment networks offer tokenized authorized schemes, and using such services for business purposes is considered safer.