1. Selling Crypto Comes with a Heavy Tax Burden
In Japan, gains from selling crypto assets are subject to comprehensive taxation at rates of up to 55%. A shift to separate self-assessment taxation is not expected until 2028, leaving holders with unrealized gains struggling to raise cash without triggering a large tax bill.
2. A $56 Billion Global Market for "Borrow, Don't Sell"
Crypto-backed loans, in which holders pledge crypto assets as collateral to borrow fiat currency, have grown into a global market of about $56 billion. In Japan, potential demand is estimated at around ¥100 billion, and a market is expected to emerge if competitive interest rates and trustworthiness can be delivered.
3. CRYL, a Domestic Crypto-Backed Loan Service
CRYL, a service that lets holders borrow Japanese yen against their Bitcoin without selling it, has launched in Japan. Loans start from ¥50,000, with annual interest rates from 3.5%. Because the collateral is not sold at the time of borrowing, no tax is incurred at that point, allowing both individuals and corporations to raise funds while keeping their positions.
When they need a substantial amount of cash, crypto holders have often had little choice but to sell.
In Japan, however, selling is not just a way to raise money. It is also a taxable event. Gains from selling crypto assets are classified as miscellaneous income and subject to comprehensive taxation, with combined income and resident tax rates reaching up to 55%. Even after realizing tens of millions of yen in profit, a holder may be left with less than half.
That situation is starting to change. In March 2026, an amendment to the Income Tax Act was enacted, shifting gains from selling crypto assets to separate self-assessment taxation at a flat rate of 20.315%. In July, an amendment classifying crypto assets as financial instruments under the Financial Instruments and Exchange Act was also passed. As a result, separate taxation is expected to apply to transfers made on or after January 1, 2028.
However, the new treatment applies only to transfers of "specified crypto assets" through domestic registered operators. Transactions on overseas exchanges and DEXs will remain subject to comprehensive taxation. Above all, immediate funding needs do not wait for regulatory reform.
Sitting on unrealized gains with no good way to use them has been a structural problem for crypto holders in Japan.
Overseas markets have already found a clear answer to this problem: pledge your assets as collateral instead of selling them.
A notable example is the crypto-backed mortgage program announced in March 2026 by U.S. mortgage lender Better and major crypto exchange Coinbase. Instead of paying the down payment in cash, borrowers can pledge Bitcoin as collateral for a separate loan that covers it. The primary mortgage is a conforming loan eligible for purchase by Fannie Mae, a government-sponsored enterprise, showing that crypto assets are beginning to be built into the U.S. housing finance system.
The required collateral is 250% of the loan amount, which is hardly lenient. Even so, borrowers can meet real-world needs without triggering capital gains tax or giving up their positions, and some holders see clear value in that. Nor is this an isolated case. According to Galaxy Research, outstanding crypto-collateralized loans peaked at about $78.7 billion (about ¥12.6 trillion) in the third quarter of 2025. Even after the market correction, they stood at about $56.2 billion (about ¥9 trillion) at the end of June 2026. "Borrow, don't sell" is becoming one of the standard options worldwide.
So what about Japan? According to the Japan Virtual and Crypto assets Exchange Association (JVCEA), crypto assets held in custody by domestic exchanges totaled about ¥5 trillion as of July 2025. That is a substantial pool of assets.
Applying the global ratio of crypto-backed loans to total crypto holdings, roughly 2%, puts Japan's potential market at around ¥100 billion (CRYL estimate). The market is there. It is simply that options for meeting this demand have been limited in Japan until now.
The demand also shows up in survey data. In [Survey 1 / Survey 2], 40.4% of crypto holders said they would consider using a crypto-backed loan. When asked what mattered most, the top answer was a low interest rate, at 31.5% [Survey 1 / Survey 2], followed by the operator's trustworthiness and how crypto assets are stored.
*Survey 1: GMO Research & AI, conducted June 2026, n=1,096. Survey 2: J-CAM Group, conducted June 2026, n=1,617. Both surveyed crypto asset holders.
Put another way, the findings suggest that a market for crypto-backed loans could take off in Japan as well, provided that interest rates and trustworthiness are addressed.
To meet the demand for funds without selling cryptocurrencies, the crypto-backed loan service 'CRYL' was launched. The mechanism is simple: by pledging your cryptocurrency holdings as collateral, you can receive a loan in Japanese yen, calculated by applying a certain margin to the appraised value of your assets.
Throughout this process, the cryptocurrency is not sold. Holders can maintain their positions while obtaining funds, and since no sale occurs, no taxable event is triggered. This structure inherently avoids the 'up to 55%' issue mentioned earlier.
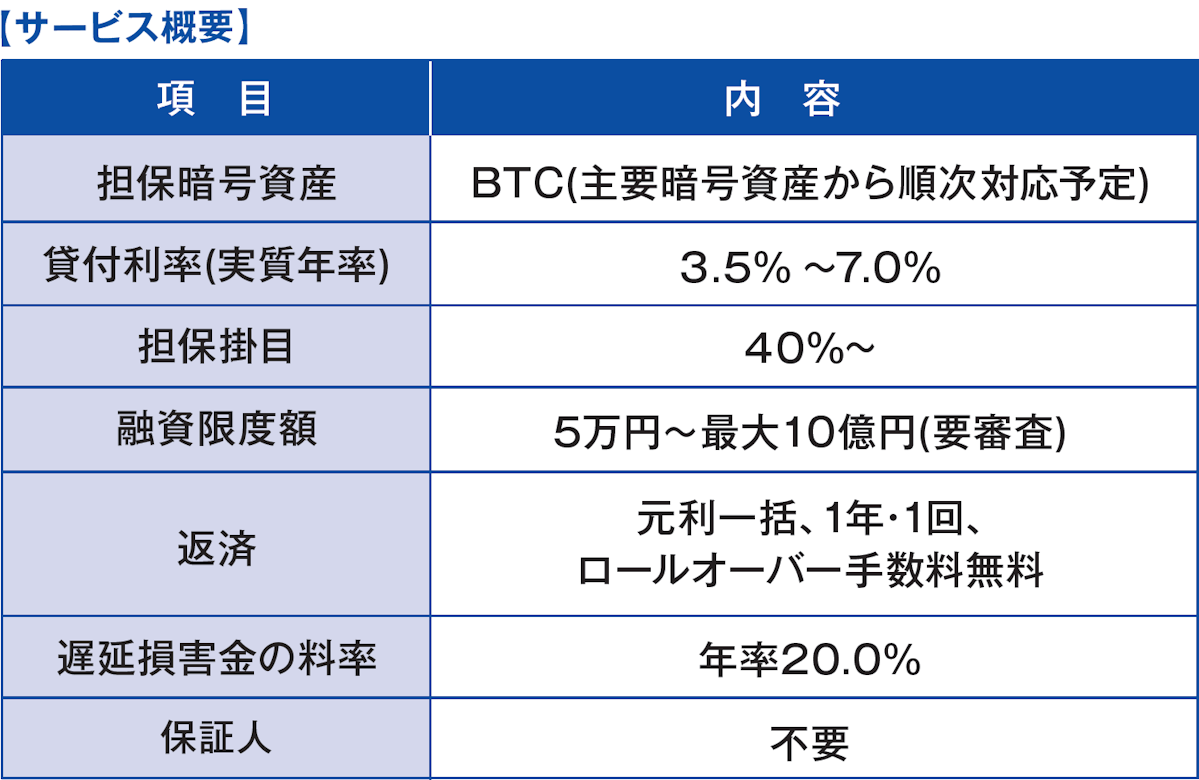
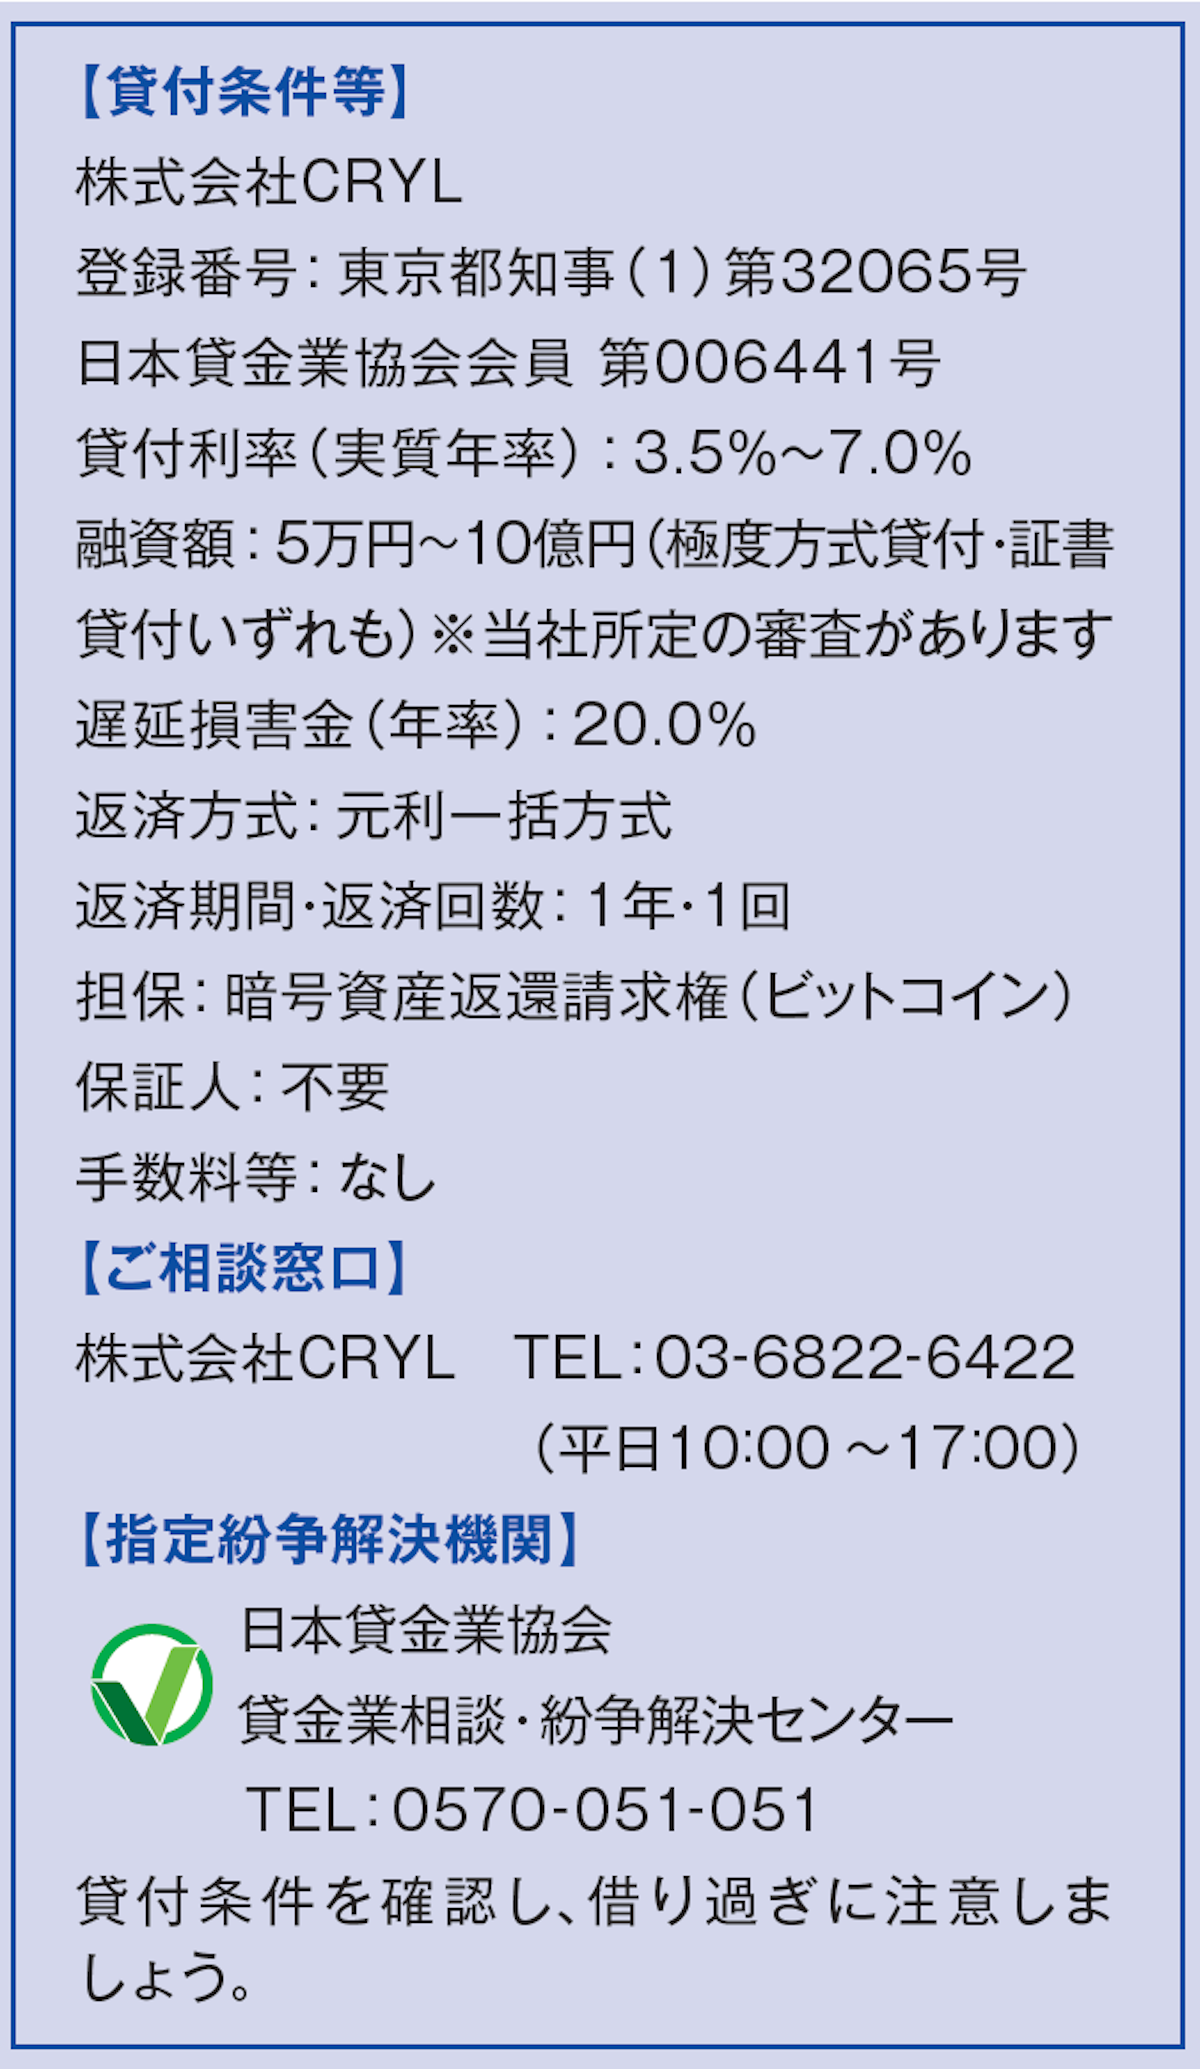
The service overview is as follows:
The minimum loan amount is 50,000 yen. Initially, transactions were handled in units of 1 million yen, but with the addition of the 'Light Plan,' which allows for smaller amounts, the option of a collateral loan is now open to those who do not require a large sum.
Interest rates are individually set based on conditions and duration, ranging from 3.5% to 7.0%. This directly addresses the most important factor for holders, as seen in the previous section, which is the low borrowing interest rate. The loan term is one year, but with no rollover fees, it is designed to easily accommodate ongoing funding needs.
The service is available to both individuals and corporations. For individuals, it offers the ability to monetize assets while maintaining long-term holdings, secure tax or living funds, or finance real estate purchases. For corporations, it provides flexible access to working capital or business funds, enhancing financial flexibility by leveraging held cryptocurrencies. Both scenarios share the common goal of meeting funding needs without liquidating positions.
However, there are points to be mindful of. If the value of the collateralized cryptocurrency significantly drops, the collateral value may fall short of the loan amount, potentially leading to forced liquidation. This is an unavoidable risk inherent to crypto-backed loans.
The service is operated by CRYL Co., Ltd., a registered moneylender under Tokyo Governor (1) No. 32065, and a member of the Japan Money Lenders Association (No. 006441).
As with any borrowing, caution is advised against over-borrowing, but the option to leverage assets without selling them is becoming available in Japan.
Visit the official website here
Image: Assets provided by Shutterstock and CRYL